Showing posts with label Valrico Fl. Show all posts

Tuesday, April 21, 2020

Will This Economic Crisis Have a V, U, or L-Shaped Recovery

Will This Economic Crisis Have a V, U, or L-Shaped Recovery?


Will this Economic crisis have a V,U, or L-shaped recovery?  Many American businesses have been put on hold as the country deals with the worst pandemic in over one hundred years. As the states are deciding on the best strategy to slowly and safely reopen, the big question is: how long will it take the economy to fully recover? 
Let’s look at the possibilities. Here are the three types of recoveries that follow most economic slowdowns (the definitions are from the financial glossary at Market Business News):
  • V-shaped recovery: an economic period in which the economy experiences a sharp decline. However, it is also a brief period of decline. There is a clear bottom (called a trough by economists) which does not last long. Then there is a strong recovery.
  • U-shaped recovery: when the decline is more gradual, i.e., less severe. The recovery that follows starts off moderately and then picks up speed. The recovery could last 12-24 months.
  • L-shaped recovery: a steep economic decline followed by a long period with no growth. When an economy is in an L-shaped recovery, getting back to where it was before the decline will take years.

What type of recovery will we see this time?

No one can answer this question with one hundred percent certainty. However, most top financial services firms are calling for a V-shaped recovery. Goldman Sachs, Morgan Stanley, Wells Fargo Securities, and JP Morgan have all recently come out with projections that call for GDP to take a deep dive in the first half of the year but have a strong comeback in the second half.

Will This Economic Crisis Have a V, U, or L-Shaped Recovery?

Is there any research on recovery following a pandemic?

There have been two extensive studies done that look at how an economy has recovered from a pandemic in the past. Here are the conclusions they reached:
1. John Burns Consulting:
“Historical analysis showed us that pandemics are usually V-shaped (sharp recessions that recover quickly enough to provide little damage to home prices), and some very cutting-edge search engine analysis by our Information Management team showed the current slowdown is playing out similarly thus far.”
2. Harvard Business Review:
“It’s worth looking back at history to place the potential impact path of Covid-19 empirically. In fact, V-shapes monopolize the empirical landscape of prior shocks, including epidemics such as SARS, the 1968 H3N2 (“Hong Kong”) flu, 1958 H2N2 (“Asian”) flu, and 1918 Spanish flu.”
The research says we should experience a V-shaped recovery.

Does everyone agree it will be a ‘V’?

No. Some are concerned that, even when businesses are fully operational, the American public may be reluctant to jump right back in.
As Market Business News explains:
“In a typical V-shaped recovery, there is a huge shift in economic activity after the downturn and the trough. Growing consumer demand and spending drive the massive shift in economic activity.”
If consumer demand and spending do not come back as quickly as most expect it will, we may be heading for a U-shaped recovery.
In a message last Thursday, Chris Hyzy, Chief Investment Officer for Merrill and Bank of America Private Bank, agrees with other analysts who are expecting a resurgence in the economy later this year:
“We’re forecasting real economic growth of 30% for the U.S. in the 4th quarter of this year and 6.1% in 2021.”
His projection, however, calls for a U-shaped recovery based on concerns that consumers may not rush back in:
“After the steep plunge and bottoming out, a ‘U-shaped’ recovery should begin as consumer confidence slowly returns.”

Bottom Line

The research indicates the recovery will be V-shaped, and most analysts agree. However, no one knows for sure how quickly Americans will get back to “normal” life. We will have to wait and see as the situation unfolds.

See our link to Red Baron Real Estate Home Page

Thursday, April 16, 2020

Think This Is a Housing Crisis? Think Again.

Think This Is a Housing Crisis? Think Again.


With all of the unanswered questions caused by COVID-19 and the economic slowdown we’re experiencing across the country today, many are asking if the housing market is in trouble. For those who remember 2008, it's logical to ask that question.
Think This Is a Housing Crisis? Think Again. Many of us experienced financial hardships, lost homes, and were out of work during the Great Recession – the recession that started with a housing and mortgage crisis. Today, we face a very different challenge: an external health crisis that has caused a pause in much of the economy and a major shutdown of many parts of the country.
Let’s look at five things we know about today’s housing market that were different in 2008.

1. Appreciation

When we look at appreciation in the visual below, there’s a big difference between the 6 years prior to the housing crash and the most recent 6-year period of time. Leading up to the crash, we had much higher appreciation in this country than we see today. In fact, the highest level of appreciation most recently is below the lowest level we saw leading up to the crash. Prices have been rising lately, but not at the rate they were climbing back when we had runaway appreciation.Think This Is a Housing Crisis? Think Again.

2. Mortgage Credit

The Mortgage Credit Availability Index is a monthly measure by the Mortgage Bankers Association that gauges the level of difficulty to secure a loan. The higher the index, the easier it is to get a loan; the lower the index, the harder. Today we’re nowhere near the levels seen before the housing crash when it was very easy to get approved for a mortgage. After the crash, however, lending standards tightened and have remained that way leading up to today.Think This Is a Housing Crisis? Think Again. | MyKCM

3. Number of Homes for Sale

One of the causes of the housing crash in 2008 was an oversupply of homes for sale. Today, as shown in the next image, we see a much different picture. We don’t have enough homes on the market for the number of people who want to buy them. Across the country, we have less than 6 months of inventory, an undersupply of homes available for interested buyers.Think This Is a Housing Crisis? Think Again. | MyKCM

4. Use of Home Equity

The chart below shows the difference in how people are accessing the equity in their homes today as compared to 2008. In 2008, consumers were harvesting equity from their homes (through cash-out refinances) and using it to finance their lifestyles. Today, consumers are treating the equity in their homes much more cautiously.Think This Is a Housing Crisis? Think Again.

5. Home Equity Today

Today, 53.8% of homes across the country have at least 50% equity. In 2008, homeowners walked away when they owed more than what their homes were worth. With the equity homeowners have now, they’re much less likely to walk away from their homes.Think This Is a Housing Crisis? Think Again.

Bottom Line

The COVID-19 crisis is causing different challenges across the country than the ones we faced in 2008. Back then, we had a housing crisis; today, we face a health crisis. What we know now is that housing is in a much stronger position today than it was in 2008. It is no longer the center of the economic slowdown. Rather, it could be just what helps pull us out of the downturn.
Visit our Website:  Red Baron Real Estate

Tuesday, March 17, 2020

Two Big Myths in the Home Buying Process


Two Big Myths in the Homebuying Process | MyKCM


Two Big Myths in the Home Buying Process:  The 2020 Millennial Home Buyer Report shows how this generation is not really any different from previous ones when it comes to homeownership goals:
“The majority of millennials not only want to own a home, but 84% of millennials in 2019 considered it a major part of the American Dream.”
Unfortunately, the myths surrounding the barriers to homeownership – especially those related to down payments and FICO® scores – might be keeping many buyers out of the arena. The piece also reveals:
“Millennials have to navigate a lot of obstacles to be able to own a home. According to our 2020 survey, saving for a down payment is the biggest barrier for 50% of millennials.”
Millennial or not, unpacking two of the biggest myths that may be standing in the way of homeownership among all generations is a great place to start the debunking process.

Myth #1: “I Need a 20% Down Payment”

Many buyers often overestimate what they need to qualify for a home loan. According to the same article:
“A down payment of 20% for a home of that price [$210,000] would be about $42,000; only about 30% of the millennials in our survey have enough in savings to cover that, not to mention the additional closing costs.”
While many potential buyers still think they need to put at least 20% down for the home of their dreams, they often don’t realize how many assistance programs are available with as little as 3% down. With a bit of research, many renters may be able to enter the housing market sooner than they ever imagined.

Myth #2: “I Need a 780 FICO® Score or Higher”

In addition to down payments, buyers are also often confused about the FICO® score it takes to qualify for a mortgage, believing they need a credit score of 780 or higher.
Ellie Mae’s latest Origination Insight Report, which focuses on recently closed (approved) loans, shows the truth is, over 50% of approved loans were granted with a FICO® score below 750 (see graph below):Two Big Myths in the Homebuying Process | MyKCMEven today, many of the myths of the homebuying process are unfortunately keeping plenty of motivated buyers on the sidelines. In reality, it really doesn’t have to be that way.

Bottom Line

If you’re thinking of buying a home, you may have more options than you think. Let’s connect to answer your questions and help you determine your next steps.

See more information and listings at:  Red Baron Real Estate

Thursday, February 27, 2020

How Much “Housing Wealth” Can You Build in a Decade?

How Much “Housing Wealth” Can You Build in a Decade?

How Much “Housing Wealth” Can You Build in a Decade? | MyKCM

How Much “Housing Wealth” Can You Build in a Decade?  Earlier this month, the National Association of Realtors (NAR) released a special study titled Single-Family Home Price Gains by Years of Tenure. The study estimates median home price appreciation over the last 30 years based on the length of homeownership.
Below are three graphs depicting the most important data revealed in the study.

How much have home prices increased?

One of the first measures of the financial benefits of homeownership is the net worth (in the form of equity) an owner can build over time. The study showed the average increase in home values based on how long homeowners stayed in a home.
How Much “Housing Wealth” Can You Build in a Decade?

What was the percentage of appreciation?

Another way to look at this is by the percentage increase in value over time, called appreciation:How Much “Housing Wealth” Can You Build in a Decade?

Was this appreciation consistent throughout the country?

Today, when we think of markets that have done well over the last decade, we have a tendency to think about San Francisco, San Diego, Seattle, and other West Coast cities. Though it is true the West Region showed the highest price growth over the last three decades, we can see how every region of the country did quite well in ten-year increments:How Much “Housing Wealth” Can You Build in a Decade?This data validates the claim that homeownership is great for building wealth. The importance of this information was highlighted in the study’s first sentence:
“Homeownership is an important source of wealth creation, enabling current homeowners and succeeding generations to move up the economic ladder.”

Bottom Line

Homeownership has many financial and non-financial benefits. The accumulation of “housing wealth” through increased equity is a major one. If you’re thinking of buying a home for the first time or moving up to your dream home, the sooner you make the move, the sooner your net worth will begin to grow.

Check out the Red Baron Real Estate Web Site For All Real Estate Needs

Friday, February 21, 2020

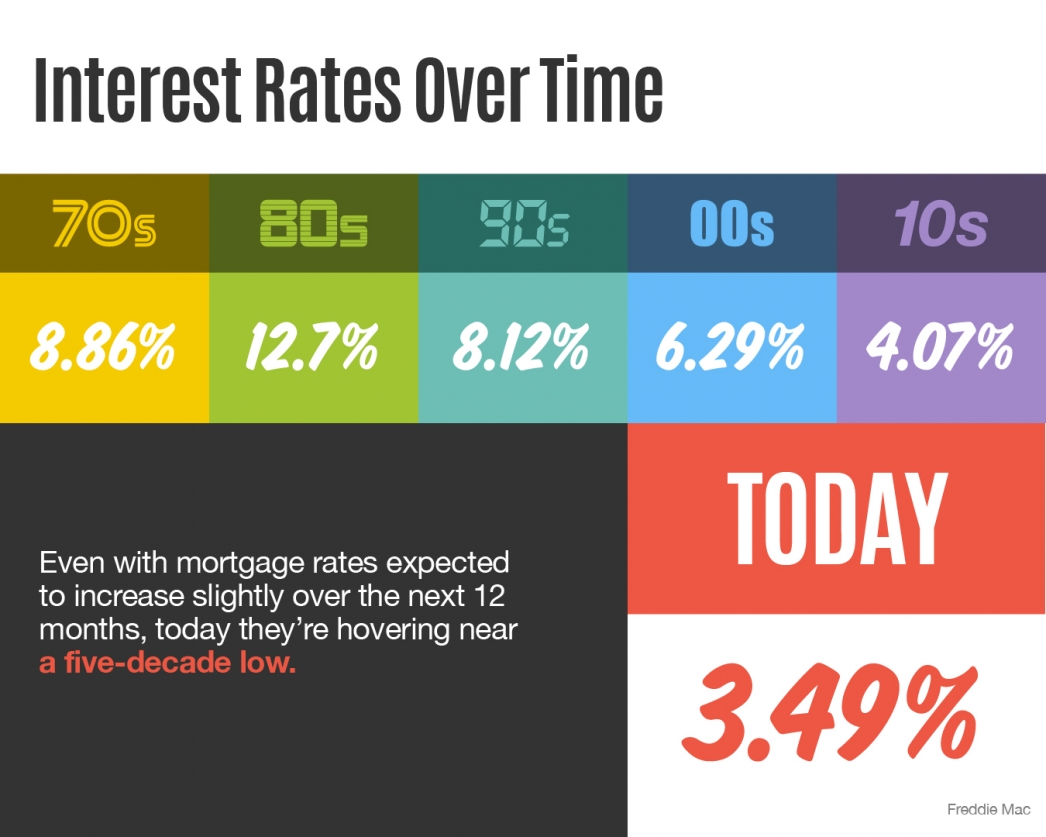
Interest Rates Over Time

Interest Rates Over Time [INFOGRAPHIC]


Interest Rates Over Time [INFOGRAPHIC] | MyKCMSome Highlights:

  • With interest rates hovering at near historic lows, now is a great time to look back at where they’ve been, and how much they’ve changed over time.
  • According to Freddie Mac, mortgage interest rates are currently hovering near a five-decade low.
  • The impact your interest rate has on your monthly mortgage payment is significant. An increase of just $20 dollars in your monthly payment can add up to $240 per year or $7,200 over the life of your loan. Maybe it’s time to lock in now while rates are still low.
Learn more at RED BARON REAL ESTATE

Monday, January 13, 2020

The New Spring Real Estate Market is Here. Are You Ready?

The New Spring Real Estate Market is Here. Are You Ready?

The New Spring Real Estate Market is Here. Are You Ready?


The new spring real estate market is here.  Are you ready?  While there is not much snow in Valrico FL, the image reminds us that that the upcoming Spring is buying season.  Which month do you think most people who are considering buying a home actually start their search? If you’re like most of us, you probably think the surge happens in the spring, likely in April. Not anymore. According to new research, January 2019 was only 1% behind February for the most monthly views per listing on realtor.com.
So, what does that mean? The busiest season in real estate has just begun.
The same research indicates,
“Historically, April launched the kickoff of the home shopping season as buyers would come out of their winter hibernation looking for their new home. However, the spring shopping season now starts in January for many of the nation's largest markets.”
With the reality of fewer homes on the market in the winter, and that supply naturally increases as we head to the spring market, waiting for more competition to list in your neighborhood this year might put you behind the curve. Perhaps now is the time to jump into the market.
George Ratiu, Senior Economist at realtor.com says,
“As shoppers modify their strategies for navigating a housing market that has become more competitive due to rising prices and low inventory, the search for a home is beginning earlier and earlier.” 
There is a lot of speculation in the market about why the search for a home is shifting to an earlier start. The one thing we do know is if you’re thinking about buying or selling a home this year, the earlier you get started, the better.
Reminder: When should you sell something? When there is less of that item for sale and the greatest number of buyers are in the market. That’s exactly what is happening in real estate right now.

Bottom Line

The new spring market for real estate is underway. If you’re considering buying or selling, let’s connect, so you have the advantage in this competitive market.
Rick Frissell, your Valrico FL Real Estate agent can help you find your perfect home. Learn about Valrico FL neighborhoods, Valrico FL suburbs, and the best places to live in Valrico FL.
You will find a wealth of useful Real Estate information for home buyers and sellers at our website! Before you buy or sell a home, be sure to either contact me or view the current market information here within my website.
My web site is intended to supply you with the most recent Real Estate market information for Bloomingdale Valrico Real Estate, Tampa Florida Real Estate, Plant City Florida Real Estate, Dover Florida Real Estate, Seffner Florida Real Estate, Brandon Florida Real Estate, Apollo Beach Florida Real Estate, Riverview Florida Real Estate, Valrico Florida Real Estate and the surrounding areas.
I feature a free, up to date and current Real Estate search that will allow you to search just like an agent. There are many places out there to search, the challenge is finding a place that offers current listings like my website. All the data is fed directly from the MLS.
As a current resident in Brandon, FL I am fully aware of the current market trends and what it takes to get a great deal on a listing or get top dollar for your current home. When it comes to getting the job done right, you can count on me.
We have a lot of connections within the Valrico FL area. Please don’t hesitate to call and ask me any questions you might have. This process is all about you and your needs. Real Estate is a big investment and I understand that. One thing you will get with me is a personal relationship, In the end, that goes a long way.
My area is a great place to live! For more information, please give me a ring or email me today. I would love the opportunity to earn your business and partner with you in regards to your Real Estate needs.

Rick Frissell aka "The Red Baron fo Real Estate"
813-340-6828


Monday, December 23, 2019

Valrico Florida Housing Inventory Is Tight

Valrico Florida Housing Inventory Is Tight


If you have followed recent posts at our website, you would see past home prices and 2020 prices have been increasing and seems to be ongoing.  There are many reasons this Valrico FL is showing phenomenal  results.  

Let's examine one of those reasons, namely "For Sale Inventory."


Why does it show "0" inventory in this stat while there are homes that are listed?  The reason is the number of listings in Valrico Fl is so low for demand it does not show as a significant measurable data point.  The 5 year average is also low at 1.4.

The "Goldie Locks' number, not to hot and not too cool, would be an index number of 6.  The number "6" translate to an equal number of buyers and sellers.

In the law of Supply and Demand, prices rise when inventory is tight and drop in markets of over supply.

Bottom Line

If considering to buy a house or even sell and buy, now is a great time to take action.  But, be prepared to take a longer search than usual.


Check this blog for related info: